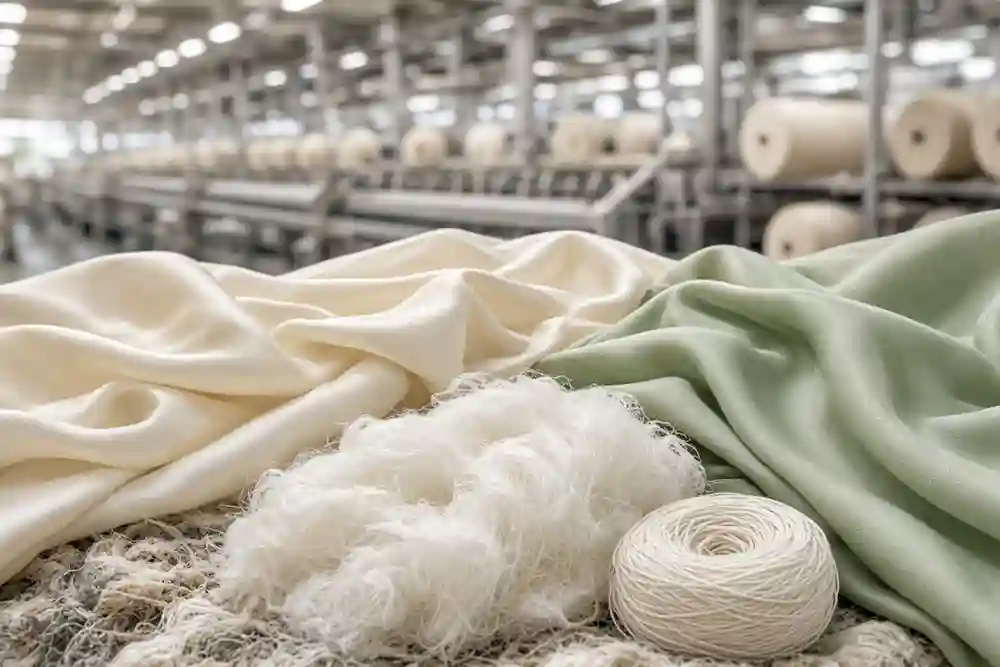
Lyocell remains a relatively small fibre category, but rapid Asian capacity expansion and demand for lower-impact cellulosics are moving competition from scarcity toward cost, quality and specialised applications.
The global lyocell fibre market could grow from about $1.84 billion in 2025 to $2.95 billion by 2032, according to QY Research, representing a 6.67% compound annual growth rate during 2026–32. China already accounts for an estimated 58.1% of market value and is forecast to reach almost 63.8% by 2032.
The forecast points to a significant restructuring of a market once associated predominantly with a handful of specialist producers.
China builds scale
QY Research identifies Lenzing, Sateri, China Textile Green Fiber, KaraFiber, HengTian Fiber Group, Yibin Grace, Tangshan Sanyou and Grasim Industries among important producers. Chinese and Indian manufacturers are increasingly pursuing larger production lines integrated with domestic spinning, weaving, nonwoven and apparel clusters.
That expansion is likely to intensify competition around production cost, consistent fibre quality, fibrillation control and application-specific grades, rather than capacity alone.
Lenzing, meanwhile, continues to position lyocell at the premium end. Its 2025 product developments included TENCEL Lyocell HV100, expanded low-fibrillation grades for knitwear and lyocell filling fibres for thermal-comfort applications.
Still small, but growing faster
Textile Exchange estimated global lyocell production at only about 0.4 million tonnes in 2024, around 5% of the 8.4-million-tonne man-made cellulosic fibre market. By 2025, total MMCF production had risen to 9.1 million tonnes, while Lenzing estimated that lyocell and modal output increased at double-digit rates.
This leaves substantial headroom compared with viscose and especially polyester.
Circularity could reshape the market
Lyocell’s next growth phase may increasingly depend on feedstock innovation. Lenzing is targeting 30% recycled content in viscose and lyocell fibres and has demonstrated lyocell containing recycled textile inputs.
For spinning mills and fabric producers, the strategic opportunity is therefore broader than substituting lyocell for cotton or viscose. Growth is emerging in denim, knitwear, home textiles, hygiene, nonwovens and functional products, while Asian capacity expansion should improve availability and sharpen pricing.
Market forecasts should nevertheless be treated cautiously: published lyocell estimates vary significantly depending on product definitions and methodology. The more useful signals to watch are actual capacity utilisation, fibre prices, Chinese expansion and adoption of recycled-content grades.