LVMH’s sharper-than-expected fashion decline suggests luxury’s three-year slowdown is not over, putting greater pressure on brands to control inventories, sharpen product innovation and protect margins.
Europe’s 10 largest listed luxury companies have lost about $350 billion in combined market value since the start of 2026, as expectations for a sector recovery have weakened and Chinese luxury demand remains subdued. LVMH, Hermès, Kering and Richemont have collectively seen their market capitalisation almost halve since around 2024, although jewellery-focused Richemont has proved relatively resilient.
LVMH fashion sales fall 5%
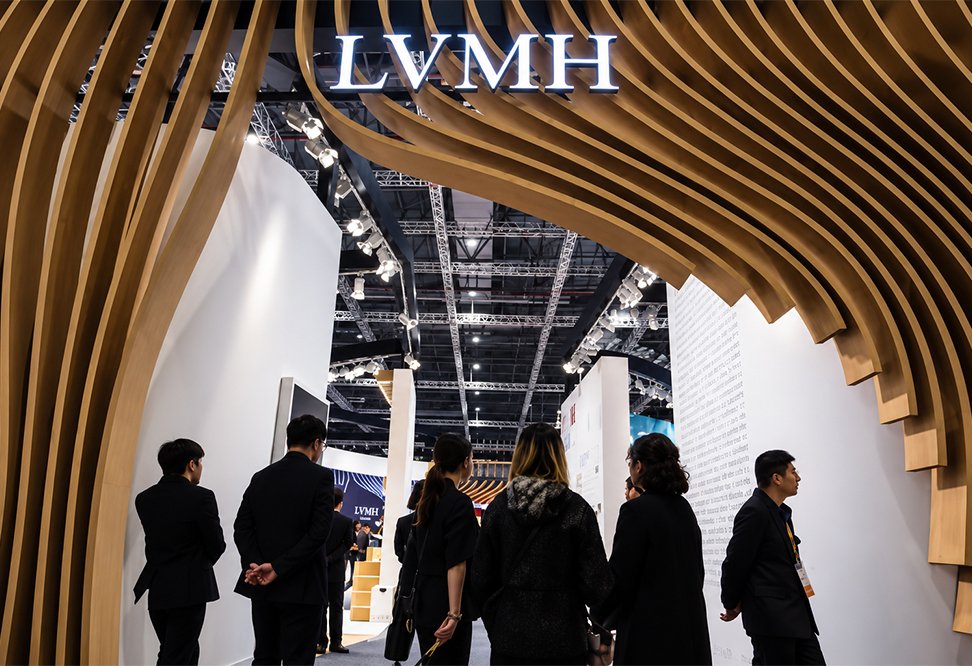
The latest warning came from LVMH, whose third-quarter organic revenue increased only 1% to €18.5 billion. Its crucial Fashion & Leather Goods division—home to Louis Vuitton and Dior—recorded a 5% organic sales decline, considerably worse than analysts’ expected 1.8% fall.
For the first nine months of 2026, LVMH generated €57.1 billion in revenue, up 2% organically, but Fashion & Leather Goods revenue fell 4% on a reported basis to €26.39 billion and 2% organically. Watches and jewellery remained stronger, with 8% organic growth over the nine months.
China loses its growth-engine role
China, once the principal engine of global luxury expansion, remains the core problem. LVMH reported a 5% decline in China-led Asian sales in Q3, while US sales rose 5%. Weak economic growth, the prolonged property downturn and tighter scrutiny of wealthy consumers continue to weigh on spending.
LVMH shares have fallen more than 40% this year, making it the biggest contributor to the sector’s valuation decline.
Textile supplier takeaway
For premium textile and apparel suppliers, slower luxury demand means greater pressure on inventory discipline, shorter development cycles, smaller production runs and product differentiation. Suppliers dependent on premium European brands should expect buyers to become more selective about fabric innovation, minimum-order flexibility and speed.
The key signal to watch is whether Chinese luxury spending stabilises in 2027. Until then, suppliers should treat the sector as a high-value but lower-volume and increasingly selective market, rather than relying on the rapid volume growth seen before the current slowdown.