The US sportswear company is cutting costs and restructuring operations, but declining consumer demand, rising freight expenses and excess inventories continue to challenge its recovery.
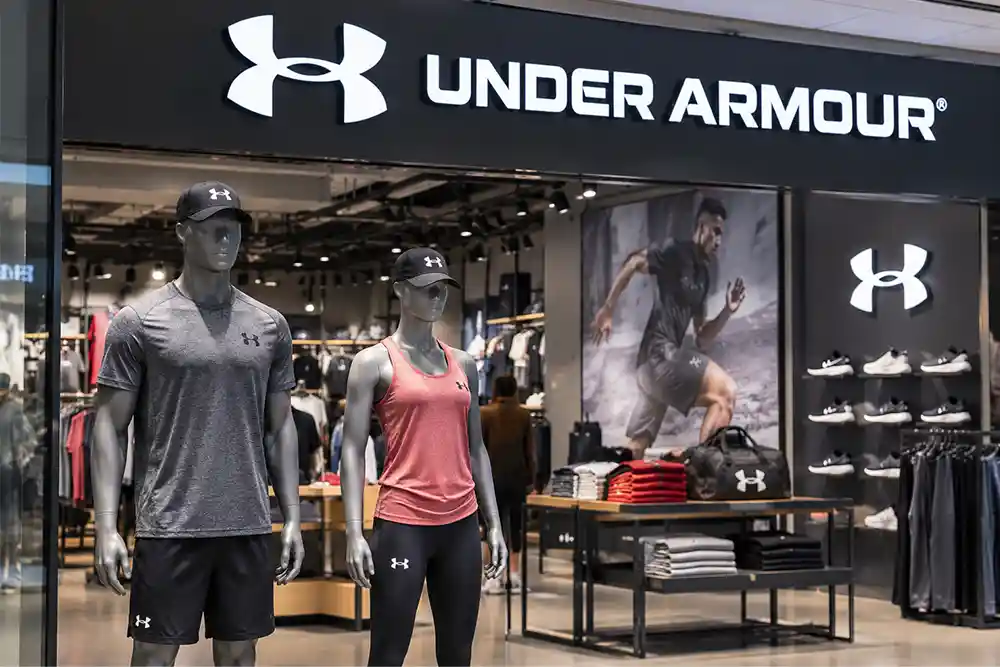
Under Armour reported a 7% decline in second-quarter FY2027 revenue to $1.24 billion, as sales weakened across major geographic markets, product categories and distribution channels.
The Baltimore-based sportswear company reported results on November 6 for the quarter ended September 30, 2026. Despite lower revenue, it modestly raised its full-year reported operating profit forecast, supported by restructuring and tighter cost controls.
Apparel and Footwear Record Broad Declines
Apparel revenue fell 6% to $880 million, while footwear sales declined 11% to $234 million. Accessories revenue decreased 7% to $105 million.
North American revenue dropped 7% to $737 million. International sales also declined 7% to $509 million, with Europe, the Middle East and Africa (EMEA) and Asia-Pacific each recording 9% decreases.
Wholesale revenue fell 6% to $725 million, while direct-to-consumer sales contracted 8% to $494 million. E-commerce performed particularly poorly, declining 12%.
Profitability Improves Through Cost Discipline
Under Armour reported operating income of $15 million, compared with adjusted operating income of $25 million. Its net loss narrowed to approximately $0.4 million.
Gross margin declined 30 basis points to 47%, reflecting currency movements, pricing pressure and changes in sales mix. Operating expenses decreased 4% to $557 million.
The company has incurred $280 million under its restructuring programme, with total costs expected to reach approximately $305 million.
FY2027 Outlook Reflects Continuing Pressure
Under Armour raised its forecast for reported operating income to $99–119 million, from $96–116 million. However, its adjusted operating income forecast remains unchanged at $140–160 million.
Full-year revenue is still expected to decline by a mid-single-digit percentage.
The company also reduced its projected gross-margin improvement to 170–220 basis points, citing higher freight costs, inventory adjustments and currency pressures.
Inventory increased 4% to $1.1 billion, signalling continued working-capital pressure.
For apparel and footwear suppliers, declining sales and elevated inventories suggest cautious purchasing and tighter order management.
The next test will be whether Under Armour can restore demand while completing restructuring by December 2026 and protecting profitability amid continued supply-chain cost pressures.